

October 9, 2026/
Gifting Shares to Family Members: Capital Gains Tax, Holdover Relief and Family...
A high earner may be tempted to place company shares in their children’s names so that dividends are taxed using the children’s personal allowances or lower tax bands. The attraction is obvious—but the tax treatment is rarely as simple as changing the names on a share register.
If a parent creates all the company’s income while the children receive its profits, HMRC will examine who funded and created the arrangement, the children’s ages, the rights attached to their shares and whether the parent continues to benefit from or control the income.
Children can legally own shares in a UK limited company. However, putting shares in their names does not automatically move the tax liability away from the parent. Dividends paid to minor children may be taxed on the parent under the settlements legislation, while arrangements involving adult children must be assessed according to genuine ownership, retained benefits, share rights and the commercial reality of the structure.
The key distinction is between:
The rules are materially different for each group.
The most restrictive rules apply where a parent gives shares, directly or indirectly, to an unmarried minor child.
Under section 629 of the Income Tax (Trading and Other Income) Act 2005, income arising from a settlement made by a parent for a minor child can be treated as the parent’s income for tax purposes.
A “settlement” is not limited to a formal trust. It can include a gift, arrangement or series of transactions involving an element of parental generosity or “bounty”.
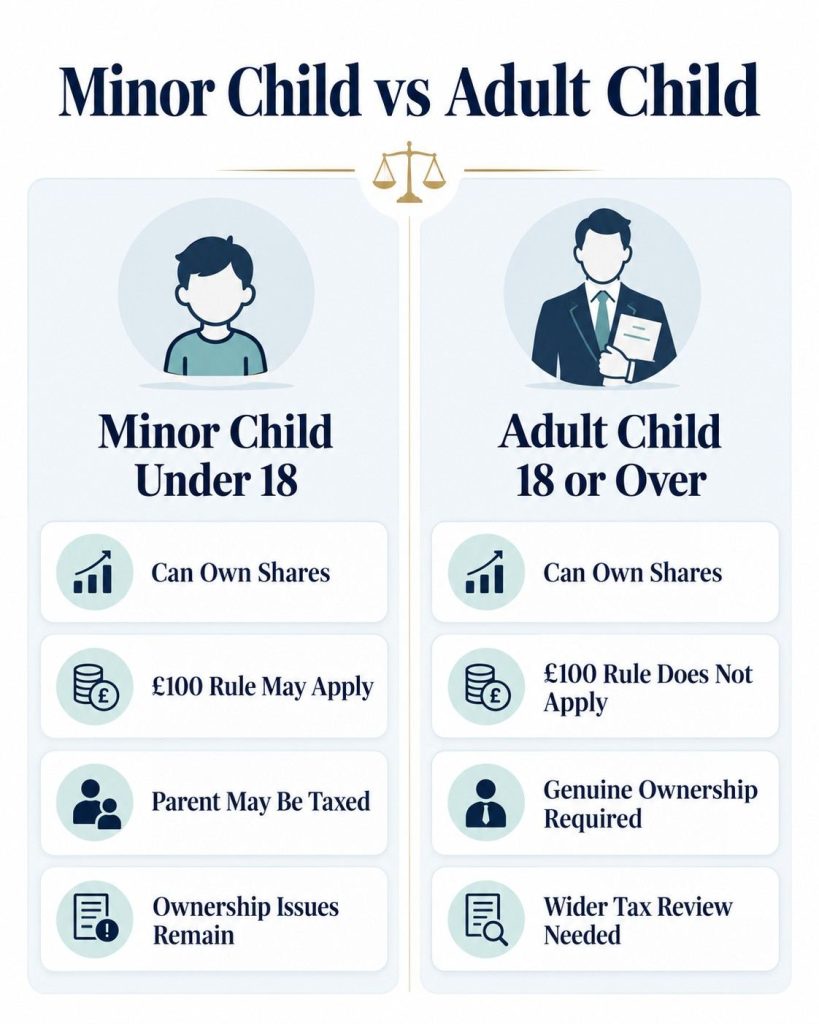
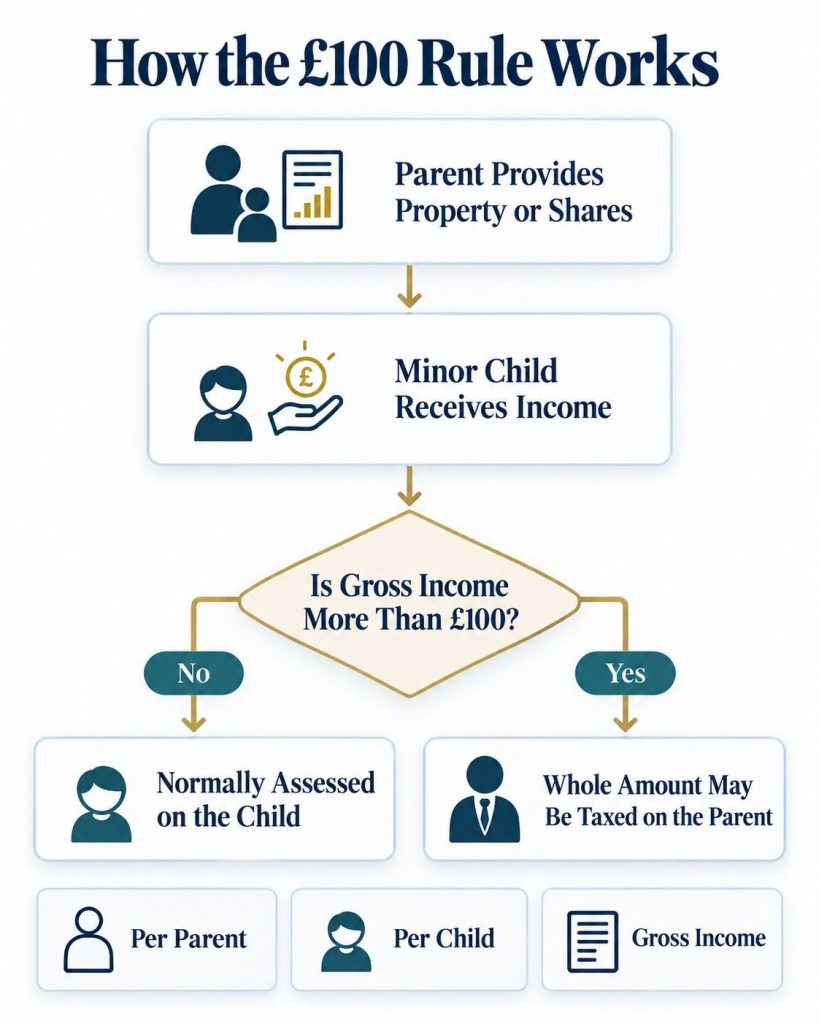
Where income arising from property provided by one parent exceeds £100 in a tax year, that income is generally taxed as the parent’s income rather than the child’s.
The £100 limit is:
If the relevant income exceeds £100, the whole amount—not merely the excess—is generally attributed to the parent.
This means that issuing or gifting shares to a minor child will not normally allow a higher-rate or additional-rate taxpayer to divert substantial dividends into the child’s unused tax allowances.
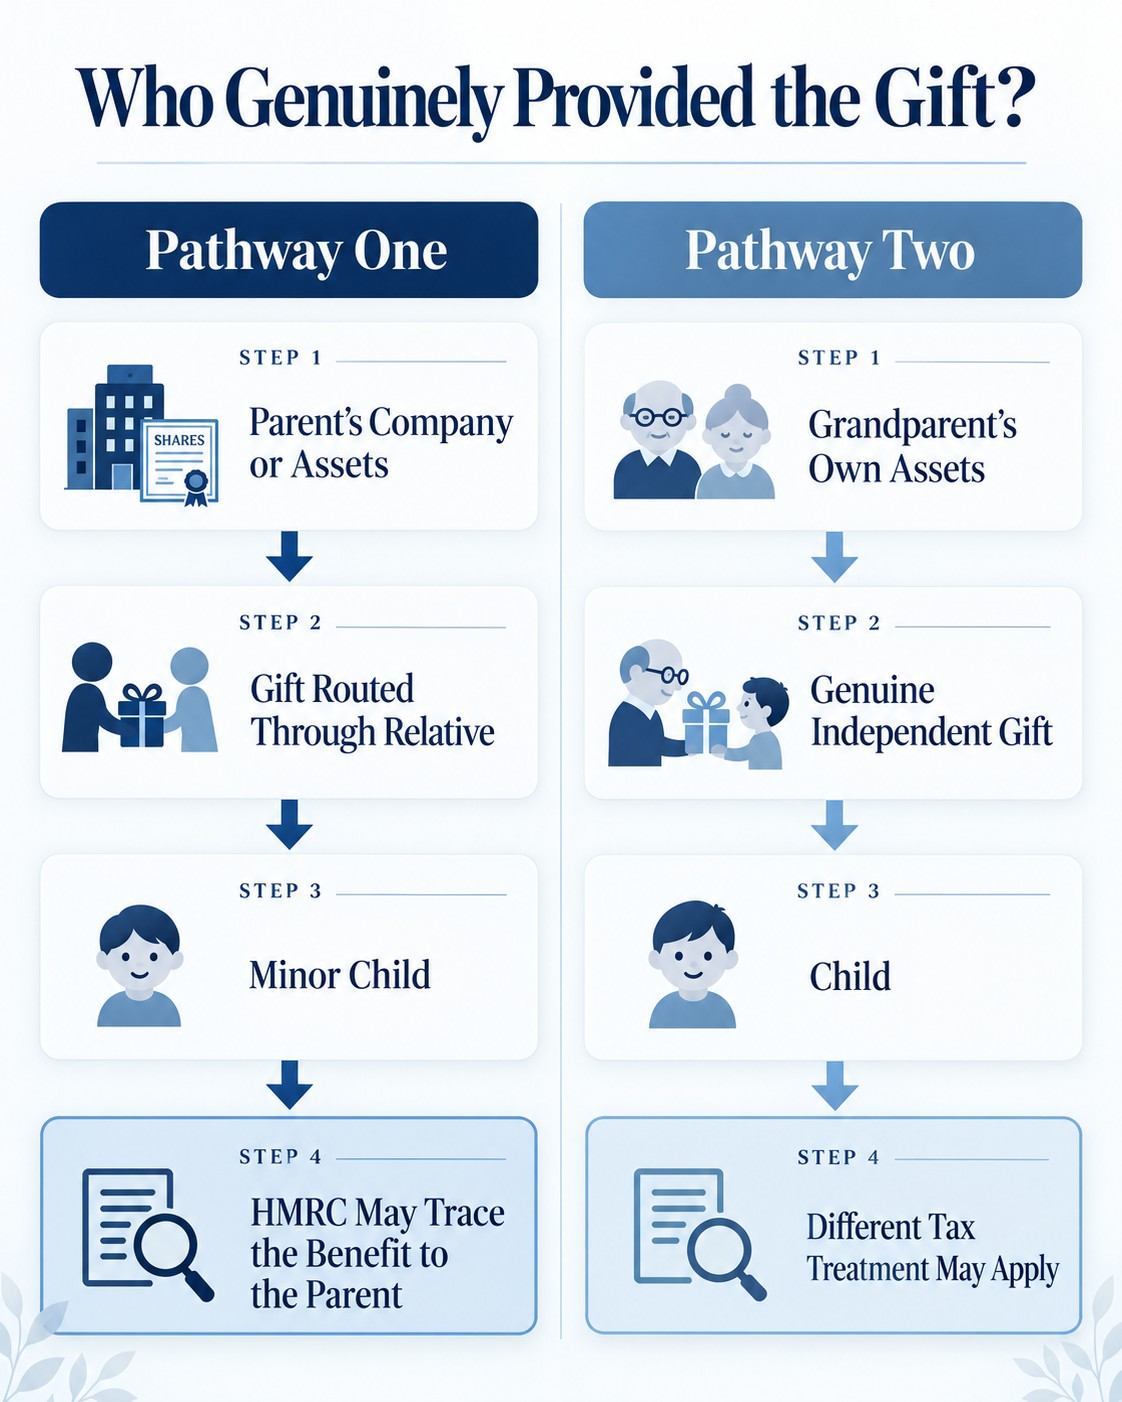
HMRC gives a particularly relevant example in its Trusts, Settlements and Estates Manual. A sole director generates the company’s profits through his own knowledge, expertise and work. Shares are routed to his minor children through their grandmother. HMRC treats the father as the true settlor and attributes the children’s dividends to him.
This illustrates an important point: inserting a grandparent or another relative into a parent-funded arrangement does not necessarily prevent HMRC from examining who really created the benefit.
Gifting Shares to Family Members: Capital Gains Tax, Holdover Relief and Family...

Sole Traders and Landlords Earning Over £30,000 Must Prepare for April 2027:...

SSAS Pension: Tax Benefits, Property Investment and Rules for Directors Home Blogs...

Business Property Relief: What the £2.5m Cap Means for You Home Blogs...
Business & Tax News and Developments September 2026 Home News Business &...

Right to Work Checks Change on 1 October 2026: What Employers Must...
The parental £100 rule does not normally apply to income arising from property genuinely provided by a grandparent or another person.
However, the gift must genuinely come from that person. A parent cannot simply route their own assets or company profits through a grandparent and assume that the parental settlement rules have been avoided.
The source of the property, the sequence of transactions and the parties’ intentions must all be considered.
A child may own shares, but a person under 16 cannot be appointed as a company director.
Even where a minor can legally hold shares, practical complications may arise. These include:
Giving shares to a child is not merely a tax entry. It may transfer genuine economic ownership and future value.
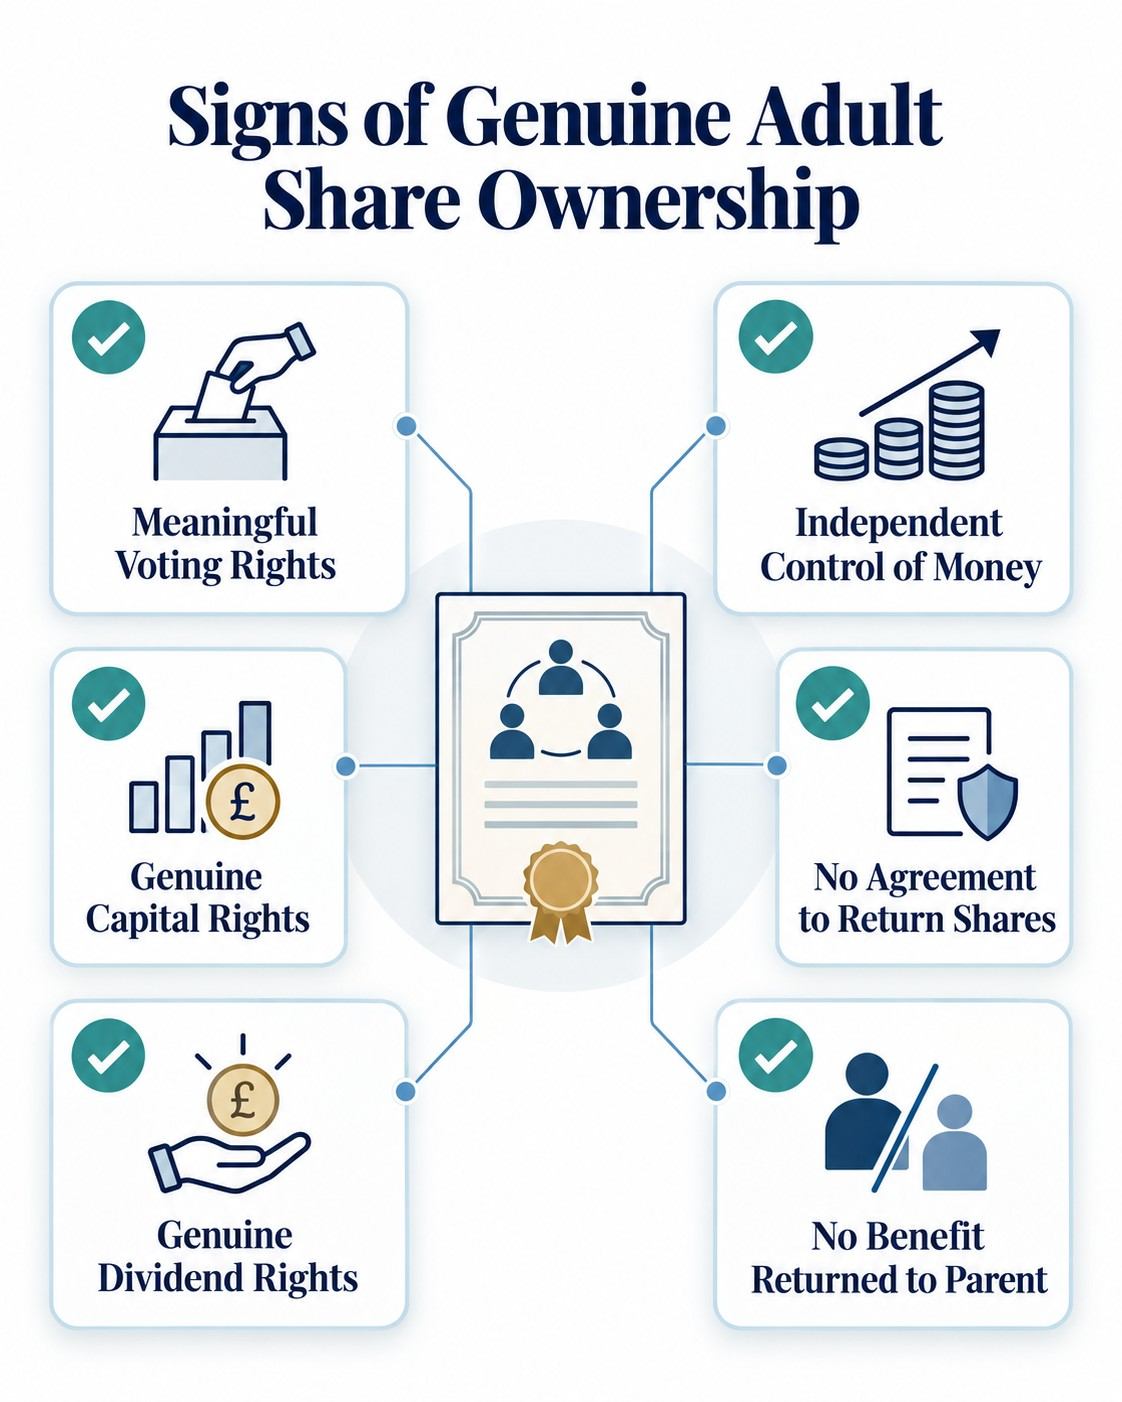
Once a child turns 18, the automatic parental £100 rule no longer applies. This does not mean that every arrangement is safe, nor does it mean that dividends are automatically taxed on the parent.
Where an adult child genuinely and beneficially owns ordinary shares, the dividends will normally be their income. This can remain the case even if the parent contributes more work to the business.
It is therefore too broad to say that HMRC will automatically tax an adult child’s dividends on the parent simply because the parent generates the company’s turnover.
The position depends on the complete arrangement.
The tax position is generally stronger where:
An adult shareholder does not necessarily have to work in the company before receiving a dividend. Dividends are returns on share ownership, not remuneration for work.
However, giving 100% of a trading company to adult children solely to access their lower tax rates—while the parent continues to generate all revenue and retains practical control—creates substantial commercial and tax risks that require detailed advice.
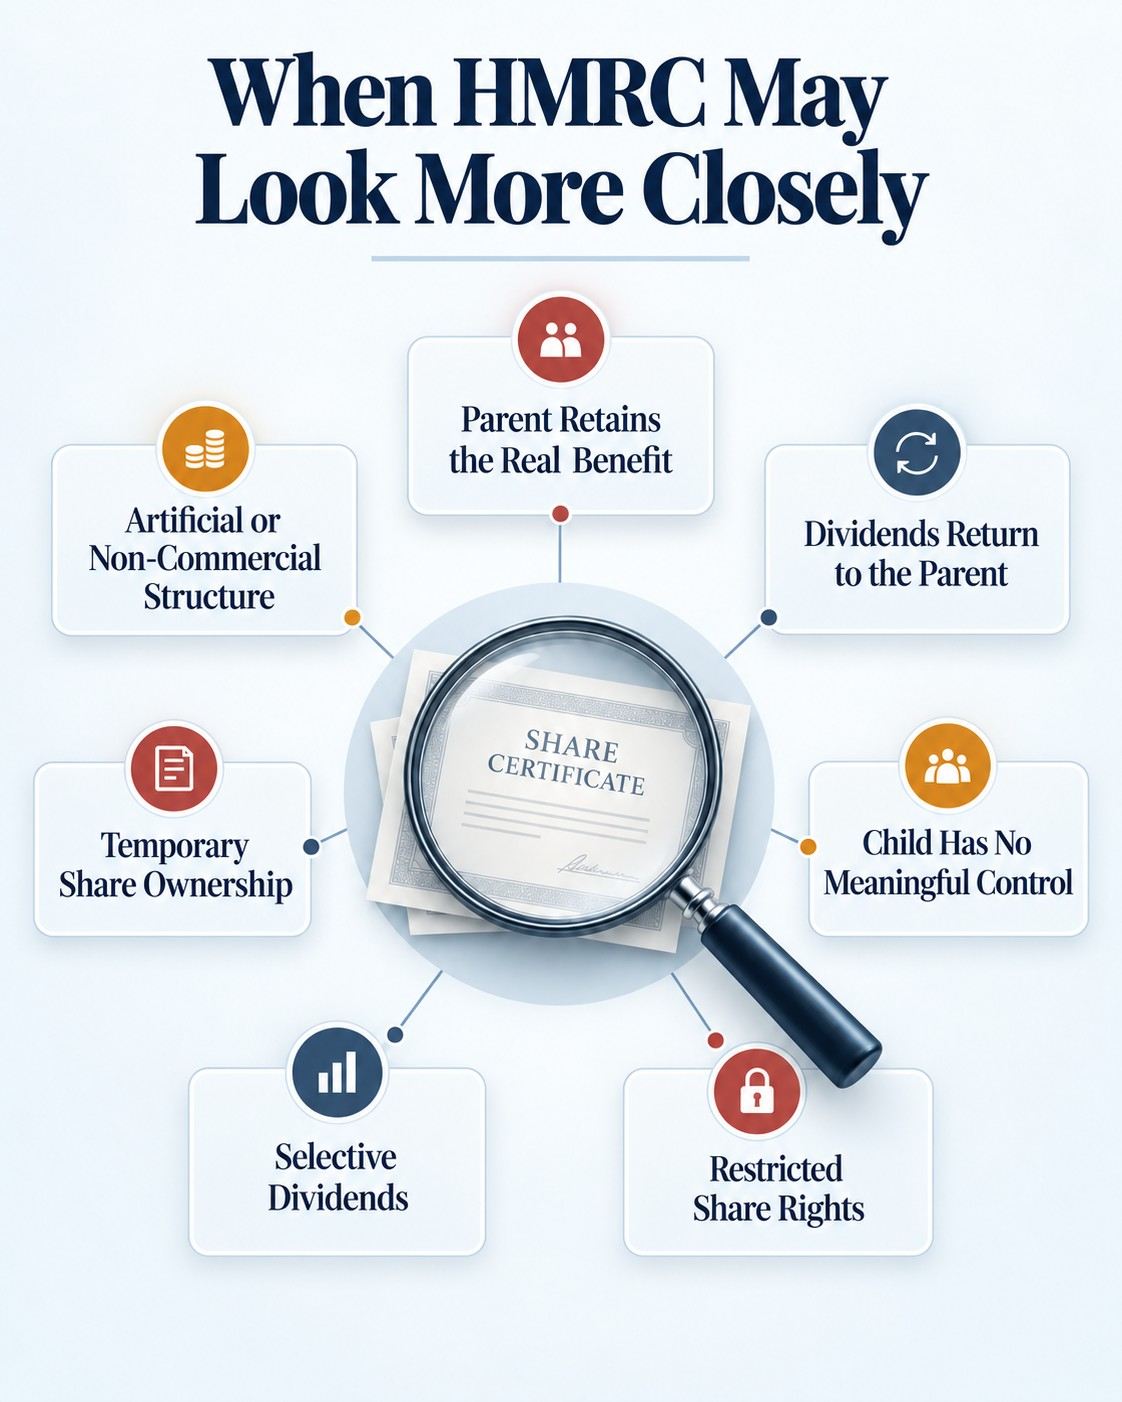
HMRC is more likely to investigate where the structure is artificial or where the paperwork does not reflect what happens in practice. Warning signs include:
HMRC’s guidance states that the whole arrangement must be considered, rather than each step in isolation. The settlements legislation may apply where an arrangement is bounteous, non-commercial or not conducted at arm’s length, particularly where the person creating the settlement retains an interest or can still benefit from the property or income.
Where the parent has genuinely and irrevocably transferred full beneficial ownership to an adult child and has not retained an interest, the analysis is more nuanced. The mere existence of a tax saving is not, by itself, enough to make the dividends the parent’s income.
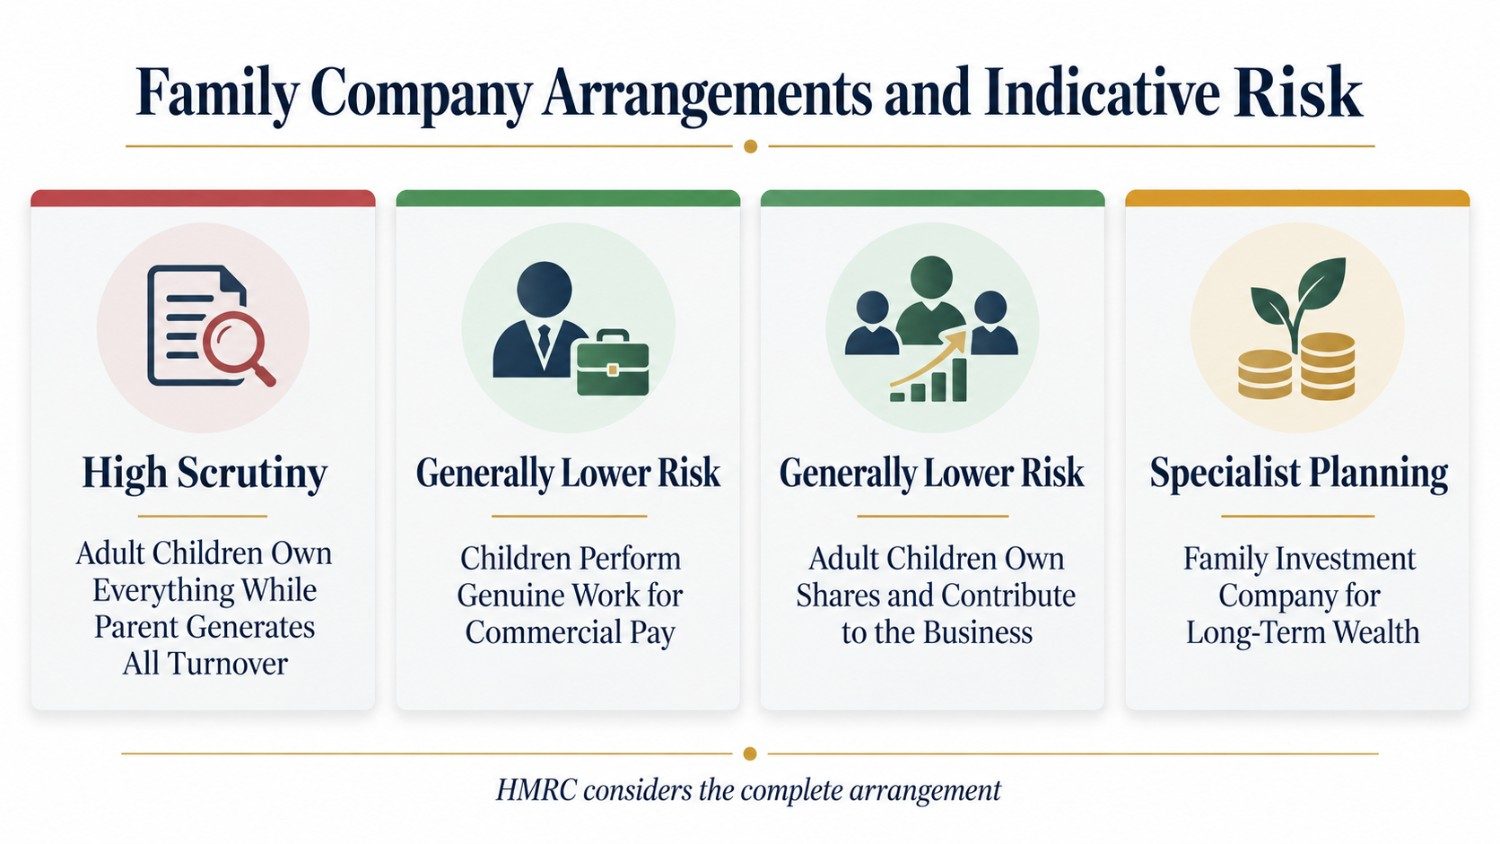
Arrangement | Indicative HMRC risk | Likely tax treatment and practical considerations |
Adult children own 100% of the shares while the parent generates 100% of the turnover | 🔴 High scrutiny | The unusual commercial position is likely to require careful examination, particularly if the structure was created mainly to divert profits into the children’s lower tax bands. However, dividends are not automatically reattributed to the parent. The outcome depends on genuine beneficial ownership, the rights attached to the shares, whether the parent retained any benefit and how the arrangement operates in practice. |
The parent employs adult children and pays a commercial salary | 🟢 Generally lower risk | The salary can normally be deducted when calculating the company’s taxable profits if the children perform genuine work and the amount is commercially reasonable. Employment contracts, working records, PAYE, National Insurance, workplace pension and National Minimum Wage requirements should be considered. |
Adult children own shares and actively contribute to the business | 🟢 Generally lower risk | A genuine family business or succession arrangement is more commercially defensible. Salary should reflect work performed, while dividends must arise from genuine share ownership and be paid in accordance with the rights attached to the shares. |
A family investment company is used for long-term family wealth planning | 🟡 Specialist planning required | A properly structured FIC can be suitable for investing family capital and transferring future growth. It is not normally an appropriate vehicle for artificially diverting one individual’s personal trading or professional income. Corporation Tax, dividend taxation, Inheritance Tax, control and succession consequences require detailed advice. |
The risk levels above are indicative only. HMRC will consider the complete arrangement, including how the shares were acquired, their legal and economic rights, who controls the company, who receives the money and whether any benefit returns to the parent.
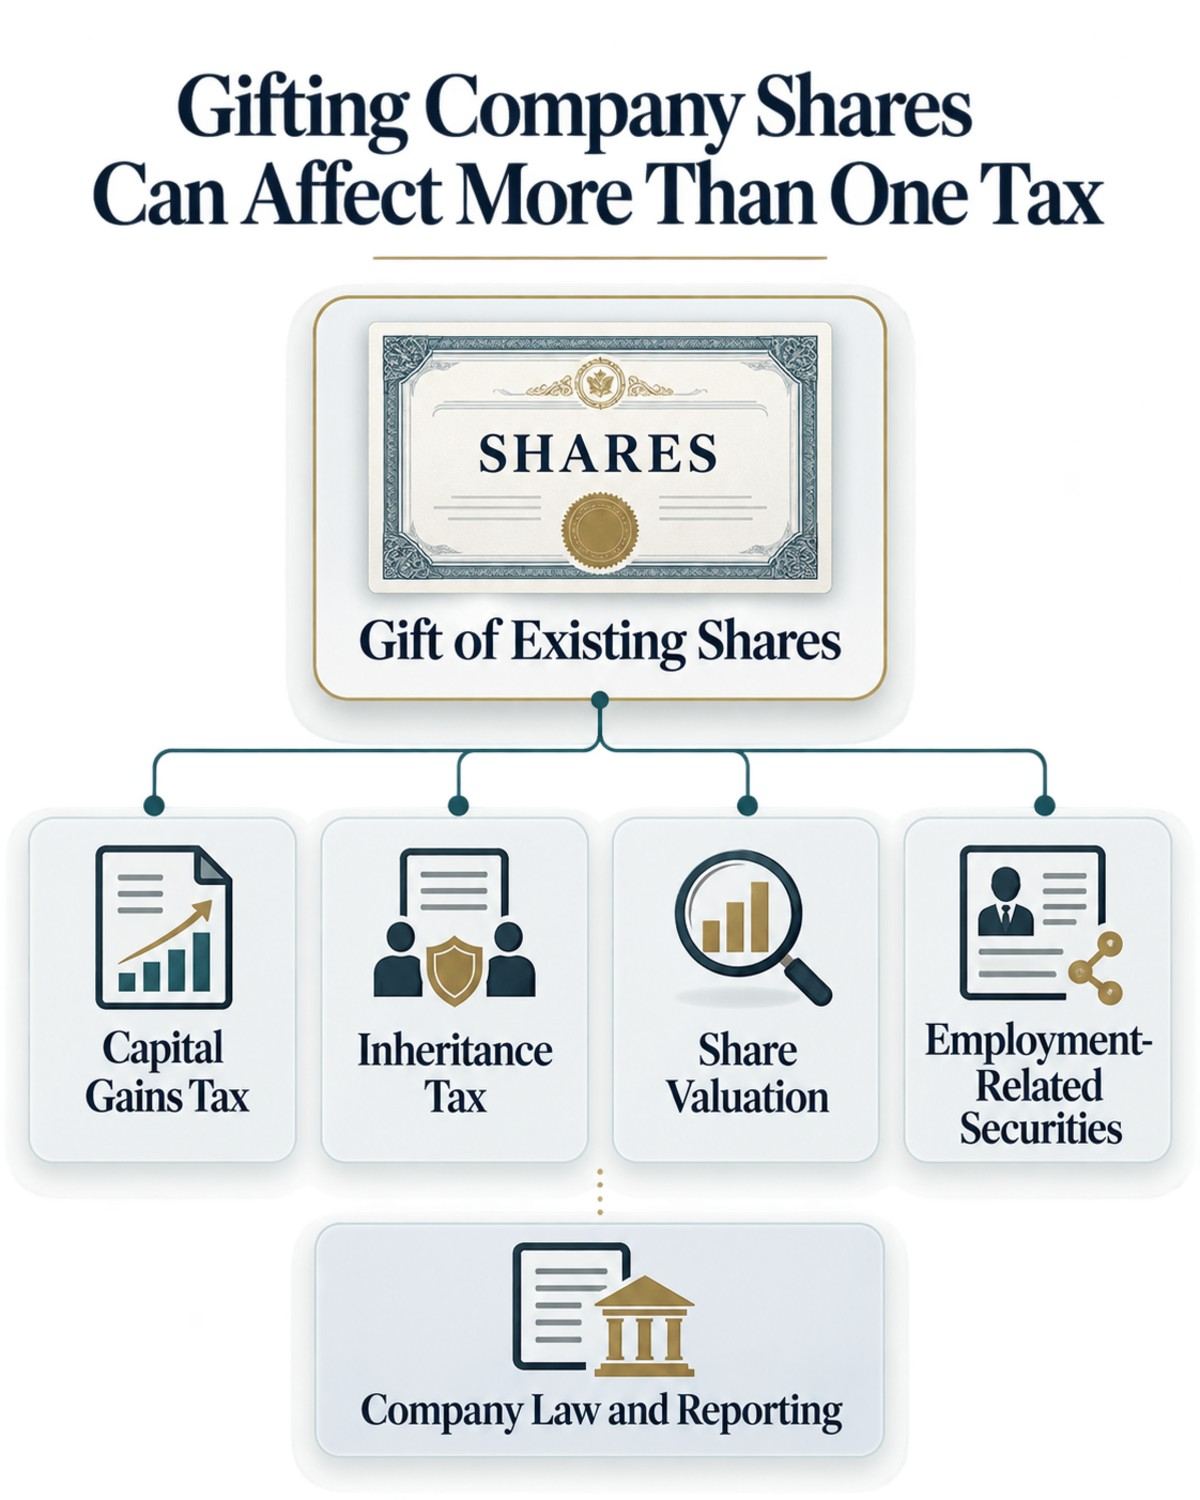
Not all shares are economically equal.
HMRC may look closely at shares which:
HMRC lists restricted shares, shares subscribed for at par and selective dividends among the factors that may indicate a settlement. That does not mean those features are automatically unlawful, but the commercial rationale and overall arrangement must withstand scrutiny.
Before issuing alphabet shares or creating different share classes, the company should review:
A flexible dividend structure should never be implemented using generic documents without first assessing the tax position.
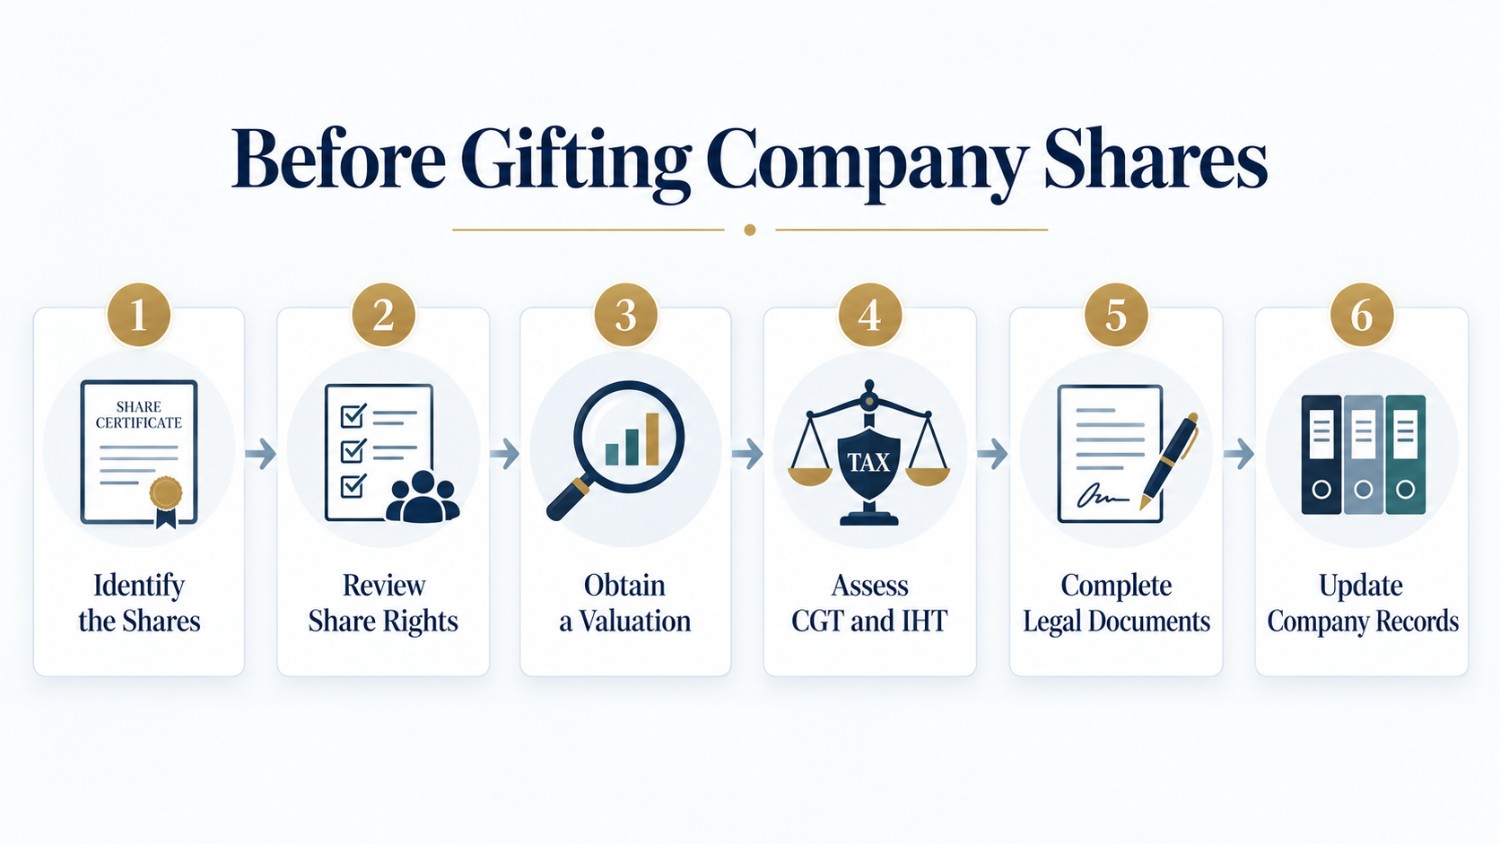
Transferring existing shares to a child can trigger tax consequences even if no money changes hands.
A gift of shares is generally treated as a disposal at market value for Capital Gains Tax purposes. Children are connected persons, so the transaction cannot normally be treated as taking place at a nominal value simply because the shares were gifted.
HMRC’s Capital Gains Manual confirms that the donor is generally treated as disposing of gifted property at its market value.
Gift Hold-Over Relief may be available for certain shares in an unlisted trading company, subject to the relevant statutory conditions. If available and properly claimed, the gain is generally deferred rather than eliminated.
Investment companies and companies with substantial non-trading activities may not qualify in the same way. A professional share valuation may therefore be required before any transfer.
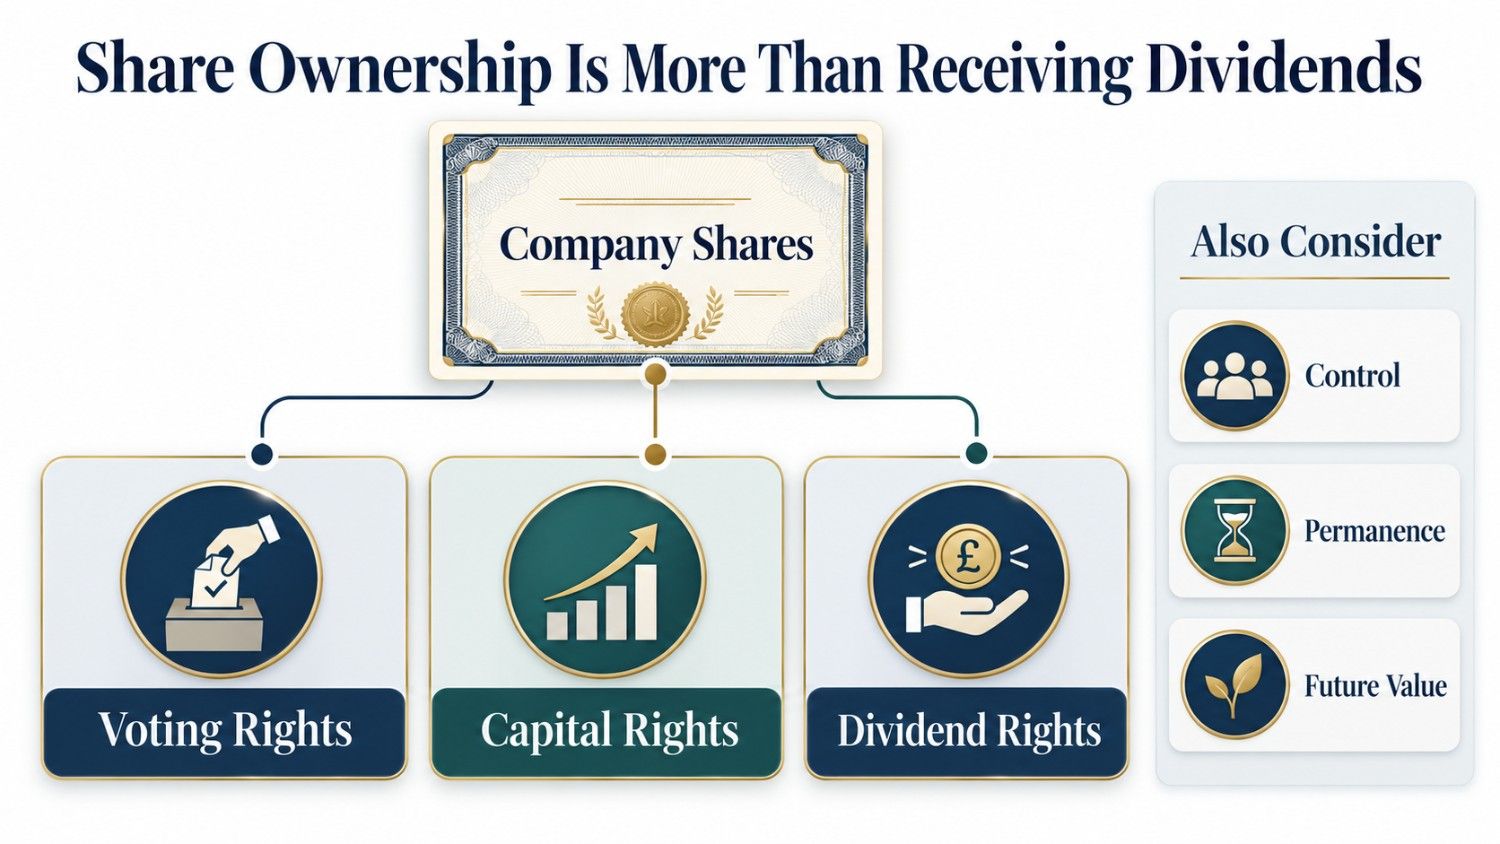
An outright gift to an adult child is normally a potentially exempt transfer for Inheritance Tax purposes. If the donor survives for seven years, the gift will generally fall outside their estate for IHT purposes.
However:
Describing every gift as “tax-free after seven years” is too simplistic. The facts and the donor’s wider estate planning must be reviewed.
Where shares are provided because a child is an employee or director, the employment-related securities rules may apply. These rules can create Income Tax consequences and HMRC reporting obligations.
The position should be reviewed before shares or options are issued—not after the company has paid dividends or increased in value.
A child who holds more than 25% of the shares or voting rights may need to be recorded as a person with significant control, depending on the precise rights and arrangements.
The company must also maintain accurate records, including:
Informal family arrangements do not displace these legal requirements.
A company can employ a director’s children, but the salary must reflect genuine work performed for the business.
Examples may include:
The company should keep evidence of:
HMRC’s guidance on payments to relatives makes clear that remuneration must be commercially justified. An excessive salary paid because of the family relationship may not be wholly and exclusively incurred for the company’s trade.
National Minimum Wage, PAYE, National Insurance, pension and child-employment rules must also be considered where relevant.
The right structure depends on whether the objective is immediate income, business succession or long-term wealth transfer.
Potential options include:
A family investment company is not a simple substitute for a trading company. It is generally used to hold and manage family investments or capital. It should not be treated as a mechanism for diverting one family member’s personal trading income to other relatives.
The weakest family company structures begin with a calculation of which family member has the lowest tax rate. The strongest begin with ownership, contribution, succession and control.
Before making children shareholders, establish:
For minor children, the settlements legislation will usually prevent a parent from using dividends to exploit the child’s unused tax allowances.
For adult children, genuine ownership can produce a different result. However, transferring or issuing shares may create Capital Gains Tax, Inheritance Tax, employment-related securities, valuation and company-law consequences. The share structure should therefore be reviewed before incorporation, allotment or transfer.
Children can be shareholders in a UK limited company, but ownership alone does not determine the tax outcome.
Dividends from parent-funded shares held by minor children are commonly attributed to the parent under the settlements legislation. Adult children are not subject to the same automatic rule, but the ownership must be genuine and the parent must not secretly retain the benefit of the shares or income.
A structure designed only to move profits into lower tax bands may produce an HMRC enquiry, additional tax, interest and potentially penalties. Properly planned family ownership, employment and succession arrangements can be legitimate—but they must reflect commercial and legal reality.
Before issuing or gifting shares to your children, obtain advice on the settlements legislation, share valuation, Capital Gains Tax, Inheritance Tax, dividend rights and Companies House requirements. Correcting an unsuitable share structure after dividends have been paid can be significantly more expensive than reviewing it in advance.
Get in touch with Naail & Co to book your free initial consultation.
Monday – Friday
9:00 am – 5:30 pm
Yes, children can own shares in a UK limited company, although the tax treatment depends heavily on their age and how they acquire the shares. Dividends from parent-funded shares held by an unmarried child under 18 may be taxed on the parent under the settlements legislation. Adult children can receive dividends in their own right where ownership is genuine and the parent has not retained the benefit.
The £100 rule applies where income from property provided by a parent exceeds £100 gross in a tax year for an unmarried minor child. Under section 629 of ITTOIA 2005, the whole income—not merely the excess over £100—is normally treated as the parent’s income. The threshold applies separately to each parent for each child and commonly affects dividends from parent-funded company shares.
HMRC normally taxes dividends on the parent where the shares were directly or indirectly provided by that parent and the relevant income exceeds £100 annually. This prevents parents from using a minor child’s personal allowance and dividend allowance to shelter their own company profits. The position can differ where the shares or investment were genuinely provided by someone else, such as a grandparent, without parental funding.
It attracts greater scrutiny where the parent generates all the company’s income but gives adult children all the dividend rights primarily to reduce tax. The dividends are not automatically taxed on the parent, but HMRC may examine beneficial ownership, retained interests, control, share rights and how the money is used. The structure is particularly vulnerable if dividends return to the parent or the children lack genuine control.
Yes, an adult child does not have to work in the business to receive dividends from shares they genuinely own. Dividends are returns on ownership, not payment for work. However, the company must have sufficient distributable profits, follow the rights attached to each share class and prepare proper dividend documentation. The arrangement must not conceal an agreement under which the parent retains or receives the economic benefit.
Transfer shares only after reviewing the commercial, tax and family consequences. Planning is particularly important before the company increases substantially in value, introduces outside investors or begins paying significant dividends. A transfer of existing shares to a child is generally treated at market value for Capital Gains Tax purposes, even if no money changes hands. Share valuation and potential Gift Hold-Over Relief should be considered before completing the transfer.
A professional valuation is strongly advisable where an established company’s shares are gifted or transferred below market value. Because a child is a connected person, the Capital Gains Tax calculation generally uses market value rather than the amount paid. A defensible valuation helps quantify any gain, support a Gift Hold-Over Relief claim where available and establish the value transferred for Inheritance Tax purposes.
The amount depends on the shares’ market value, original cost, company activities and the reliefs available. A gift may create a market-value disposal for Capital Gains Tax, although Gift Hold-Over Relief may sometimes defer the gain on qualifying unlisted trading-company shares. The transfer may also be a potentially exempt transfer for Inheritance Tax. No reliable figure can be calculated without valuing the shares and reviewing the company.
Yes, a company can employ a director’s children for genuine work and pay them a commercially reasonable salary. The company can normally deduct the cost when calculating taxable profits if the expense is incurred wholly and exclusively for the trade. Duties, hours and payments should be documented, while PAYE, National Insurance, National Minimum Wage, workplace pension and child-employment requirements must be addressed where applicable.
The most common mistake is treating the arrangement as a simple tax-saving exercise while ignoring genuine ownership and control. Once shares are transferred, the child may acquire enforceable rights to dividends, voting power and future sale proceeds. Problems also arise from restricted share rights, selective dividends, missing valuations, inadequate company records and money returning to the parent. The full structure should be reviewed before shares are issued or transferred.


Gifting Shares to Family Members: Capital Gains Tax, Holdover Relief and Family Succession Planning Home Blogs Gifting Shares to Family...

Business Exit Planning: What Owners Should Check Home Blogs Business Exit Planning: What Owners Should Check Table of Contents Share...

Self Assessment for Company Directors: New Reporting Rules for 2025/26 Home Blogs Self Assessment for Company Directors: New Reporting Rules...


Subscribe to our newsletter to receive our weekly feed.

69-71 Lambeth Walk London SE11 6DX
Monday – Friday 9:00 am – 5:30 pm
Subscribe to our newsletter
Follow us
Download from
Services
DROP US A LINE
Copyright 2024 Naail & Co | Designed by Orion Global Consulting. | Naail & Co is the trading name of Naail & Co Ltd | Company registration number 08606377 | VAT registration number 170 3380 31


